



Himalayan Salt Lamps

10 Benefits of Himalayan Salt Lamps for Your Bedroom
Himalayan pink salt lamps have gained popularity as an interior design trend. Himalayan pink salt, which has a natural pink-red tint due to minerals, is
Natural Himalayan Rock Salt Lamp – Buy Himalayan Salt Crystal Lamp Online – Rangdaar – Rangdaar
Casinos that accept bank cheque in the UK remain a niche but relevant category in 2026, because a small but stubborn segment of players still prefers paper over pixels. The cheque has outlived fax machines, phone banking, and half the e-wallets that launched with great fanfare and quietly folded. While the average UK casino withdrawal now clears in under 10 minutes via debit card or Skrill, a bank cheque takes between 5 and 10 working days to arrive and another few to clear once deposited. That is roughly 40 times slower than a fast-payout casino, and yet cheque withdrawals persist for a specific reason: traceability. Every cheque carries a paper trail that both the issuing bank and the receiving bank can audit, which matters more than convenience for players who treat gambling winnings as taxable-adjacent income or who simply do not trust digital wallets with their banking details.
The honest picture is that most online casinos in the UK dropped cheque support years ago. The UK Gambling Commission (UKGC) does not require operators to offer cheque as a withdrawal method, and the cost of processing paper instruments — courier fees, manual verification, returned-cheque handling — pushed operators toward instant alternatives. But a handful of operators, particularly those with land-based casino heritage like Genting Casino, and certain bingo and lottery brands, still keep the cheque option alive for withdrawal. For players who want the reassurance of a physical instrument, or who need documentation that a digital transfer simply cannot provide, casinos that accept bank cheque in the UK represent a deliberate, if slow, choice.
This guide covers everything a UK player needs to know about cheque gambling in 2026: which operators still support it, how the process works end to end, what it costs in time and fees, how it compares with faster alternatives, and whether the cheque route makes any sense at all given the current market. The analysis draws on the operators active in the UK market, the regulatory framework under which they operate, and the practical realities of moving money through the UK banking system in 2026.
A bank cheque withdrawal from an online casino follows a process that has barely changed in twenty years, which tells you something about both the instrument and the casinos that still offer it. The player requests a cheque payout through the casino cashier, the operator issues a physical cheque drawn on their corporate bank account, a courier delivers it to the player’s registered address, and the player deposits it into their own bank account. Each step introduces a delay, and each delay is measured in days rather than minutes.
Step one is the request. The player logs into the casino, navigates to the withdrawal section, and selects bank cheque as the payout method. Most operators that still support cheques set a minimum withdrawal threshold for this method, typically higher than for e-wallets or debit cards, because the per-cheque processing cost is fixed regardless of amount. A £50 cheque costs the operator roughly the same to issue and courier as a £500 one, so casinos discourage small cheque requests with minimums in the £50 to £100 range.
Step two is internal processing. The casino’s finance team verifies the withdrawal request, checks that all wagering requirements have been met, confirms the player’s identity and address, and then authorises the cheque. This stage alone takes 1 to 5 working days depending on the operator, and it is the stage where most complaints originate. Players who submitted KYC documents late, or whose address on file does not match their bank records, find their cheque delayed by weeks while the compliance team sorts things out.
Step three is courier delivery. Once issued, the cheque travels by tracked courier to the player’s registered address. UK domestic courier delivery typically takes 1 to 3 working days, but the casino will only send to the address on file — the same one verified during KYC — so there is no redirection option. Miss the delivery and the cheque goes back to the operator, restarting the process from step two.
Step four is bank clearing. The player deposits the cheque into their own account, and the bank places a hold while it clears. Under the UK’s cheque clearing system (the Image Clearing System, or ICS), most cheques clear within one working day of deposit, with funds available the next. But “clearing” and “available” are not the same thing: banks may still impose an additional hold on cheque deposits, particularly for larger amounts or accounts with limited history. A £2,000 cheque from a casino might sit in a player’s account for two or three days before the bank releases it, even though the ICS technically cleared it the day before.
Total elapsed time, from request to funds in hand: 7 to 14 working days under ideal conditions. Compare that with the fastest UK casino withdrawals, which clear in 15 minutes to 2 hours via Skrill, Neteller, or PayPal, and the cheque route starts to look less like a payment method and more like a test of patience.
The operator list below reflects the brands active in the UK market in 2026 that are known to keep cheque withdrawal as a payout option, or that operate in categories (land-based casinos, bingo halls, lottery brands) where cheque support has historically been maintained. This is not a claim that every operator on this list currently offers cheque at all times — payment method availability varies by account, region, and operator policy, and operators update their cashier sections without fanfare. What the list represents is the set of UK-facing brands where cheque withdrawal has been a documented option and remains plausible in 2026.
BetMGM entered the UK market with significant marketing spend and a product range that spans sports, casino, and live dealer games. As a major international brand with US roots, BetMGM’s payment infrastructure is built around debit cards, PayPal, and bank transfer, with cheque support historically limited. For UK players specifically, cheque withdrawal availability at BetMGM is inconsistent — the brand leans heavily toward digital methods, and the cheque option, where it exists, tends to appear only for larger withdrawal amounts after extended account history.
Virgin operates in the UK gambling space through its casino and bingo verticals, and the brand’s approach to payments reflects its broader consumer-services philosophy: keep it simple, keep it digital. Virgin casino accounts are set up primarily around debit cards and e-wallets. Cheque withdrawals are not a headline feature, and players looking for this method at Virgin will likely find bank transfer offered as the paper-trail alternative instead — slower than a cheque in some cases, but without the courier dependency.
BetVictor is one of the more established names in UK gambling, with a history stretching back to Victor Chandler’s bookmaking operations. The brand has modernised its payment suite considerably, and cheque support has receded as faster methods took priority. For most BetVictor UK players in 2026, withdrawals run through debit cards, PayPal, or bank transfer. Cheque remains a possibility for long-standing accounts with large withdrawal histories, but it is not a standard offering.
LottoGo operates in the lottery and instant-win space, a category where cheque withdrawals have deeper roots because lottery winnings, particularly larger prizes, have traditionally been paid by cheque or bank draft. LottoGo’s product is built around syndicate play and number betting, and the payment methods reflect that: bank transfer and debit card dominate, with cheque available for certain prize tiers. For players who treat lottery-style play as their primary casino activity, LottoGo is one of the more plausible places to encounter a cheque payout.
bwin is a major European operator with a significant UK presence, and its payment infrastructure is extensive. The brand supports a wide range of withdrawal methods including debit cards, PayPal, Skrill, Neteller, and bank transfer. Cheque support at bwin UK has been limited in recent years, with the operator prioritising speed and digital methods. Players seeking a paper trail from bwin are more likely to use bank transfer, which provides documentation without the courier step.
Sky Bet, part of the Flutter Entertainment group (which also owns Paddy Power and Betfair), operates primarily as a sports betting brand with casino and bingo products. Flutter’s payment strategy across its brands is heavily digital, and cheque withdrawal is not a standard feature at Sky Bet. The group’s focus on app-based betting and instant withdrawals means that cheque support, where it exists at all, is an edge case rather than a menu option.
Sun Bingo operates under the tabloid brand and targets a demographic that has historically been more receptive to traditional payment methods. Bingo players, on average, skew older than sports bettors, and operators serving this demographic have been slower to drop cheque support. Sun Bingo’s payment options include debit cards, PayPal, and bank transfer, with cheque available for certain withdrawal scenarios. The brand’s connection to traditional British media and its audience profile make it one of the more likely places to find cheque still on the cashier menu.
The Pools Casino Free Spins 2026: A Veteran’s Guide to What’s Actually Worth Your Time
Admiral (spelled with a capital L in some brand contexts) is part of the Novomatic group and operates both online and land-based gambling venues in the UK. Land-based casino operators have a natural connection to cheque payments because their physical venues have always handled cash, cheques, and bank drafts as part of normal operations. Admiral’s online offering supports debit cards and bank transfer, and cheque withdrawal is plausible for players who also hold accounts at their physical venues, where cheque handling is part of the standard cashier process.
Gala Bingo is one of the largest bingo brands in the UK, with both online and physical hall operations. The Gala brand, now part of the Entain group, serves a player base that includes a significant proportion of older adults who may prefer traditional payment methods. Gala Bingo’s online cashier supports debit cards, PayPal, and bank transfer, and cheque withdrawal has historically been available for larger amounts. The combination of physical venues and an older demographic means Gala is among the more credible operators for cheque support in 2026.
Genting Casino is the operator on this list with the strongest physical connection to cheque payments. Genting operates land-based casinos across the UK, and their physical venues have always handled cheques as part of normal cashier operations. The Genting online casino supports debit cards, bank transfer, and other digital methods, but the brand’s heritage in land-based gambling means cheque withdrawal is more naturally integrated into their payment ecosystem than at pure-play online operators. For UK players who want a casino where cheque is not an afterthought, Genting Casino is the most credible option on this list.
None of these operators should be assumed to hold a specific UKGC licence number based on their inclusion here — the list is compiled from market presence and historical payment method documentation, not from a licence registry check. What matters for the player is the practical question: can I get my money by cheque from this operator, and if so, how long will it take?
Best Live Casino UK 2026: Where the Tables Are Real and the Math Is Not in Your Favour
The table below compares the ten UK-market operators on the dimensions that matter for cheque-seeking players. All characteristics are typical for this category of operator and payment method — individual operator terms vary, and players should verify current conditions in the casino cashier before requesting a cheque withdrawal. The “cheque likelihood” column reflects the operator’s historical support for cheque payments and the structural factors (land-based heritage, demographic profile, product category) that make cheque support more or less plausible in 2026.
| Operator | Typical Bonus | Typical Min. Deposit | Typical Withdrawal Speed (Digital) | Cheque Likelihood | Category |
|---|---|---|---|---|---|
| BetMGM | Deposit match up to £100 | £10 | 1–3 working days | Low — digital-first | Casino / Sports |
| Virgin | Free spins or small deposit match | £10 | 1–3 working days | Low — digital-first | Casino / Bingo |
| BetVictor | Deposit match or free spins | £5–£10 | 1–2 working days | Low — legacy accounts only | Casino / Sports |
| LottoGo | Free plays or bonus credits | £5–£10 | 2–5 working days | Moderate — lottery category | Lottery / Instant Win |
| bwin | Deposit match up to £100 | £10 | 1–3 working days | Low — bank transfer preferred | Casino / Sports |
| Sky Bet | Free bets or small bonus | £5 | Same day to 1 working day | Very low — app-focused | Sports / Casino |
| Sun Bingo | Deposit match + free bingo tickets | £10 | 2–5 working days | Moderate — older demographic | Bingo |
| Admiral | Deposit match or free spins | £10 | 2–5 working days | Moderate — land-based heritage | Casino (online + physical) |
| Gala Bingo | Deposit match + free bingo tickets | £10 | 2–5 working days | Moderate to high — physical venues | Bingo |
| Genting Casino | Deposit match or free spins | £10 | 3–7 working days | High — land-based cashier heritage | Casino (online + physical) |
The pattern in the table is clear: operators with land-based casino or bingo hall operations, or those serving older demographics, are more likely to keep cheque support alive. Pure-play online brands — Sky Bet, BetMGM, bwin — have moved decisively toward digital methods, and cheque appears in their payment ecosystems only as a legacy option for specific account types. The typical bonus figures above are representative of the category, not guaranteed offers; welcome bonuses change frequently, and the actual terms at any operator should be checked directly.
Bank cheque gambling is entirely legal in the UK, and the payment method itself falls under normal banking regulations rather than gambling-specific rules. The UK Gambling Commission regulates casino operators, not payment methods — an operator can offer any withdrawal method it chooses, provided it meets the general requirements around anti-money laundering (AML), know-your-customer (KYC) verification, and responsible gambling safeguards. There is no UKGC rule that requires operators to offer cheque withdrawals, and equally no rule that prohibits them.
The regulatory framework that touches cheque gambling comes from two directions. From the gambling side, the UKGC’s Licence Conditions and Codes of Practice (LCCP) require operators to process withdrawals “as soon as is reasonably practicable” after a player’s identity and funds have been verified. This is deliberately vague — it does not define a maximum timeframe, and it does not mandate specific payment methods. A casino that offers cheque withdrawals and processes them within 10 working days is not technically in breach of the LCCP, provided the delay is attributable to the payment method rather than to operator negligence.
From the banking side, cheque handling in the UK is governed by the Cheque and Credit Clearing Company (C&CCC) and the Image Clearing System (ICS), which was fully implemented across UK banks in 2019. Under ICS, cheques are scanned at the point of deposit and the image, rather than the physical paper, is cleared between banks. This has reduced clearing times from the old four-day cycle to next-day clearing in most cases, but it has not changed the fundamental reality that cheque deposits involve a hold period and are slower than electronic transfers.
For UK players, the legal position is straightforward: you can request a cheque withdrawal from any licensed operator that offers it, and you can deposit that cheque into any UK bank account. There are no tax implications specific to cheque gambling — gambling winnings are not taxable in the UK for recreational players, regardless of the payment method used to receive them. The only regulatory consideration that matters practically is AML: casinos must verify the source of funds for large withdrawals, and a cheque for £10,000 will trigger the same identity and source-of-funds checks as a £10,000 bank transfer. The payment method does not change the regulatory burden; it just changes how long the money takes to reach you.
The operators that still support cheque withdrawals are not limited to a narrow slice of casino games — they offer the same broad range of products as their digital-first competitors, because cheque support is a payment infrastructure decision, not a product decision. A player at Genting Casino or Gala Bingo has access to the same slots, table games, live dealer tables, and bingo rooms as a player at Sky Bet or BetMGM. The cheque is simply one of several ways to get money in and out.
Slots dominate the gamecatalogue at every operator on this list, and the reason is simple mathematics: slots carry the highest house edge per spin of any casino game, typically between 2% and 12% depending on the title, which means they generate more revenue per player-hour than blackjack (house edge around 0.5% with basic strategy) or baccarat (around 1.06% on banker bets). Operators structure their game lobbies around slots because that is where the money is, regardless of whether the player eventually withdraws by cheque or by PayPal.
Live dealer games have become the second pillar of modern casino lobbies, and the cheque-friendly operators are no exception. Evolution Gaming and Pragmatic Play supply live blackjack, roulette, baccarat, and game-show-style titles to most UK-facing casinos, and the live format appeals to a demographic that skews slightly older and more table-game oriented than the pure slots crowd. For cheque-seeking players — who, as noted, tend to be older and more traditional in their banking habits — the live casino floor is often the primary draw. The irony is not lost on anyone: the player who wants a paper cheque for their winnings is often the same player who prefers a human dealer spinning a physical wheel over a random number generator.
Bingo products, available at Sun Bingo and Gala Bingo specifically, occupy their own category with their own payment patterns. Bingo players tend to deposit smaller amounts more frequently than casino players, and they withdraw smaller amounts more often too. This creates a tension with cheque withdrawals, which carry fixed processing costs that make small payouts uneconomical for operators. Most bingo brands handle this by setting higher minimums for cheque withdrawals — typically £50 or more — and by steering players toward debit cards or PayPal for routine payouts. Cheque remains available for larger withdrawals, but it is not the default.
Lottery-style products at LottoGo follow a different pattern again. Lottery winnings, particularly syndicate payouts and larger prize tiers, have historically been paid by cheque or bank draft because the amounts involved justify the processing overhead and because lottery operators want a documented paper trail for tax and audit purposes. LottoGo players who win significant amounts are more likely to encounter a cheque payout than players at any other operator on this list, simply because the product category demands it.
Sports betting products at Sky Bet, bwin, BetVictor, and BetMGM are the least likely to involve cheque withdrawals, for the obvious reason that sports bettors tend to be younger, more app-dependent, and more impatient with slow payment methods. The average sports bettor in the UK withdraws winnings within hours of a successful bet, and the thought of waiting 10 working days for a cheque is antithetical to the instant-gratification culture of sports betting. These operators have invested heavily in instant withdrawal technology precisely because their customer base demands it, and cheque support has withered as a result.
The UK online casino market in 2026 offers players a wide range of withdrawal methods, each with its own speed profile, fee structure, and minimum threshold. Bank cheque sits at the slow end of this spectrum, but it is not the slowest option available — some bank transfer methods, particularly international transfers or transfers to certain account types, can take as long or longer than a cheque. The table below compares the major withdrawal methods available at UK-facing casinos, with typical processing times, fees, and minimum amounts.
| Withdrawal Method | Typical Processing Time | Typical Fee | Typical Minimum | Best For |
|---|---|---|---|---|
| Bank Cheque | 7–14 working days | £0–£25 (operator-dependent) | £50–£100 | Players needing paper trail |
| Debit Card (Visa/Mastercard) | 1–3 working days | Free | £5–£10 | Most players, most situations |
| PayPal | Same day to 24 hours | Free | £5–£10 | Speed without sharing bank details |
| Skrill | Same day to 24 hours | Free (casino-side) | £10 | Regular players, VIP tiers |
| Neteller | Same day to 24 hours | Free (casino-side) | £10 | Regular players, VIP tiers |
| Bank Transfer (FPS/BACS) | 1–5 working days | Free to £5 | £10–£50 | Larger amounts, documentation needs |
| Apple Pay / Google Pay | 1–3 working days | Free | £5–£10 | Mobile-first players |
The fee structure around cheque withdrawals deserves particular attention because it is where operators recover their processing costs. Some casinos absorb the cheque fee as a courtesy to players; others pass it on directly, charging anywhere from £5 to £25 per cheque issued. A £25 cheque fee on a £200 withdrawal represents 12.5% of the payout — a substantial haircut that no e-wallet withdrawal would incur. Players considering cheque withdrawals should calculate the effective cost of the method, including fees, before committing to it.
Minimum withdrawal thresholds also work against cheque as a routine payment method. Most operators set the cheque minimum at £50 or higher, compared with £5 to £10 for debit cards and e-wallets. For a player who wins £30 on a slots session and wants to cash out, cheque is simply not an option — the minimum is too high. This structural disadvantage means cheque withdrawals are realistically reserved for larger payouts, which in turn means the player is waiting longer for a larger sum, and the opportunity cost of that delay is proportionally greater.
Speed comparisons make the trade-off explicit. A Skrill withdrawal from a fast-payout UK casino can clear in 15 minutes under optimal conditions — the operator processes the request, Skrill receives the funds, and the player can spend or transfer them immediately. A bank cheque for the same amount takes 7 to 14 working days to arrive, plus another 1 to 3 days for bank clearing. The player waiting for a cheque is, in effect, lending the casino an interest-free loan for two weeks. At a hypothetical 4% annual return on a £500 withdrawal, that two-week delay costs the player roughly £1.07 in foregone interest — small in absolute terms, but it illustrates the principle: slow payments have a cost, even when no fee is charged.
Requesting a cheque withdrawal from a UK online casino is a process that rewards patience and punishes haste. The steps below describe the typical workflow, but individual operators vary in their specific requirements and timeframes. Players should treat this as a general guide rather than a universal procedure, and should confirm the current terms in their casino’s cashier section before initiating a cheque request.
Step one is account verification. Before any withdrawal method can be used — cheque included — the casino must have completed KYC verification on the player’s account. This means government-issued photo ID (passport or driving licence), proof of address (utility bill or bank statement dated within the last three months), and in some cases proof of payment method ownership. Players who have not completed KYC will find their cheque request blocked at the first hurdle, and the verification process itself can take 24 to 72 hours depending on the operator’s compliance team workload.
Step two is the withdrawal request itself. The player navigates to the cashier, selects withdrawal, chooses bank cheque as the method, and enters the amount. The casino’s system will enforce the minimum withdrawal threshold for cheques — typically £50 to £100 — and will reject requests below that amount. Some operators also impose maximum cheque limits, often in the £2,000 to £5,000 range per transaction, requiring players with larger balances to split their withdrawal across multiple cheques or switch to bank transfer for the excess.
Step three is the wagering requirement check. If the player has claimed a bonus, the casino verifies that all wagering requirements have been met before processing the cheque. This is the stage where many players discover, to their frustration, that their “winnings” are still locked behind a 40x playthrough requirement on a £50 bonus — meaning they need to wager £2,000 before a cheque can be issued. The wagering requirement is the casino’s insurance policy against bonus abuse, and it applies equally to cheque withdrawals as to any other method.
Step four is processing and issuance. The casino’s finance team reviews the request, confirms that the account is in good standing, verifies that the withdrawal amount is within limits, and authorises the cheque. This stage takes 1 to 5 working days at most operators, and it is the stage where delays accumulate if there are any discrepancies — a name mismatch between the casino account and the bank account, an expired ID document, or an address that does not match the one on file.
Step five is courier delivery. The cheque is dispatched by tracked courier to the player’s registered address. The player must be available to receive the delivery or must arrange for someone else at the address to sign for it. Courier companies typically make two or three delivery attempts before returning the parcel to the sender, and a returned cheque means the entire process restarts from step four — another 1 to 5 working days of processing, another courier dispatch, another delivery attempt.
Step six is bank deposit and clearing. The player deposits the cheque into their own bank account, either at a branch, through a banking app (most UK banks now support cheque deposits via mobile), or by post. The bank places the funds on hold while the cheque clears under the Image Clearing System, which typically takes one working day. After clearing, the funds become available, though some banks impose an additional hold on cheque deposits — particularly for amounts over £1,000 or for accounts that have not previously received cheque deposits.
Bonus offers at UK online casinos are structured to give the operator an edge, and the wagering requirements attached to those bonuses are the mechanism by which that edge is enforced. For players at cheque-friendly casinos, bonus terms matter more than at fast-payout casinos, because the combination of wagering requirements and cheque processing delays creates a double wait: first for the playthrough to be completed, then for the cheque to arrive and clear.
The typical welcome bonus at UK-facing casinos in 2026 falls into three categories: deposit match bonuses, free spins offers, and no-deposit bonuses. Deposit match bonuses are the most common, offering to match a player’s first deposit by a percentage — typically 100% up to £100 or 200% up to £50. The wagering requirement on these bonuses ranges from 20x to 65x the bonus amount, with 35x to 40x being the market median. A £50 bonus with a 40x wagering requirement means the player must wager £2,000 before any winnings from the bonus can be withdrawn.
Free spins offers carry their own wagering requirements, typically applied to the winnings from the free spins rather than to the spins themselves. A common structure is 50 free spins with a 35x wagering requirement on any winnings — if the free spins generate £20 in winnings, the player must wager £700 before those winnings become withdrawable. Free spins are often restricted to specific slot titles, which limits the player’s ability to choose games with favourable return-to-player (RTP) percentages to meet the wagering requirement efficiently.
No-deposit bonuses — the “free money” offers that attract the most attention — carry the highest wagering requirements of all, typically 50x to 100x the bonus amount, and the lowest maximum withdrawal caps, often £50 to £100. A £10 no-deposit bonus with a 60x wagering requirement means the player must wager £600 before withdrawing, and even then the withdrawal is capped at £100. These bonuses are marketing tools designed to get the player through the door, not to generate payouts, and the maths makes that abundantly clear.
For cheque withdrawals specifically, bonus terms add an additional layer of complexity. Some operators exclude cheque withdrawals from bonus-related winnings entirely, meaning that any funds derived from a bonus cannot be withdrawn by cheque and must be cashed out through an alternative method. Others allow cheque withdrawals but impose higher minimums or longer processing times for bonus-derived funds. Players who intend to use cheque as their primary withdrawal method should read the bonus terms carefully before claiming any offer, because the interaction between wagering requirements and payment method restrictions can turn a seemingly generous bonus into a locked account.
The UK online casino market continues to launch new brands each year, and the question of whether new casinos support cheque withdrawals has a predictable answer: almost never. New operators entering the UK market in 2026 are building their payment infrastructure around digital methods from day one, because that is what their target demographic expects and because the cost of cheque processing — courier accounts, manual verification workflows, returned-cheque handling — is a significant overhead for a startup operation with thin margins.
The operators launching in the UK in 2026 tend to fall into two categories: international brands expanding into the UK under a UKGC licence, and UK-focused startups targeting specific niches (live casino, crash games, instant-win products). Neither category has a structural reason to offer cheque withdrawals. International brands bring their existing digital payment infrastructure, which is built around e-wallets and debit cards. UK-focused startups are competing on speed and convenience, and cheque support would be a competitive disadvantage in that context.
For players who specifically want cheque support, the practical implication is clear: stick with established operators that have historical ties to land-based gambling or older demographics. New casinos may offer larger welcome bonuses, more generous loyalty programmes, or more innovative game selections, but they will not offer cheque withdrawals, and a player who signs up at a new casino expecting this option will be disappointed.
There is one exception worth noting: some new operators launching with land-based venue partnerships do integrate cheque support into their payment infrastructure from the start, because the physical venue’s cashier operations already handle cheques as a matter of routine. These operators are rare in the 2026 UK market, but they exist, and players who prioritise cheque support should research an operator’s physical venue connections before opening an account.
The choice between cheque, e-wallets, and bank transfer as a casino withdrawal method comes down to three variables: speed, documentation, and cost. Each method optimises for different priorities, and the “best” method depends entirely on what the player values most.
E-wallets — PayPal, Skrill, Neteller — optimise for speed. Withdrawals clear in the same day or within 24 hours at most UK casinos, and the funds are immediately available for spending, transfer, or reinvestment. The documentation trail is weaker than a cheque: e-wallet transactions appear on the player’s e-wallet statement but not on their bank statement until the player transfers funds from the e-wallet to their bank account. For players who need a clear paper trail linking casino activity to their bank account, e-wallets are a poor choice.
Bank transfer optimises for documentation without the courier dependency. A BACS or Faster Payments transfer from a casino to a player’s bank account appears directly on the player’s bank statement, with the casino’s name and the transaction amount clearly visible. Processing times range from 1 to 5 working days, which is faster than a cheque but slower than an e-wallet. The cost is typically free or nominal (under £5), and the minimum withdrawal is usually £10 to £50. For most players who want documentation, bank transfer is the pragmatic middle ground.
Cheque optimises for documentation and physicality. The player receives a physical instrument that they can hold, deposit, and reference in future correspondence. The paper trail is the strongest of the three methods: the cheque itself, the courier tracking record, and the bank’s deposit receipt all create a documented chain of custody. But the speed penalty is severe — 7 to 14 working days versus 1 to 5 for bank transfer versus same-day for e-wallets — and the cost, where charged, is the highest of the three methods.
The opportunity cost calculation favours e-wallets for most players. A £1,000 withdrawal held up for 10 working days in cheque processing, at a conservative 4% annual return, costs the player roughly £1.10 in foregone interest. That is trivial in isolation, but it scales with the amount and the delay: a £10,000 withdrawal delayed for 14 working days costs roughly £15.34 in foregone interest, and a player who makes four such withdrawals a year is losing £61.36 annually to cheque processing delays — money that goes to the casino’s float account rather than the player’s.
The UK Gambling Commission’s responsible gambling framework applies to all payment methods equally, and cheque withdrawals are no exception. Operators must provide players with tools to control their gambling — deposit limits, loss limits, session time limits, self-exclusion, and reality checks — regardless of whether the player eventually withdraws by cheque, debit card, or e-wallet. The
payment method itself does not change the operator’s obligations, but it does change the player’s experience of those obligations in practice.
The responsible gambling tools that matter most for cheque-seeking players are deposit limits and session time limits, because the cheque withdrawal process introduces a unique psychological dynamic. A player who requests a cheque withdrawal and then waits 10 working days for it to arrive is, during that waiting period, in a state of financial limbo — the money is neither in the casino account (where it could be gambled again) nor in the player’s bank account (where it could be spent on real-world expenses). This limbo state can trigger impulsive re-deposits: the player, bored or frustrated by the wait, opens the casino app, deposits fresh funds from their debit card, and starts gambling again while the cheque is still in transit.
Operators are aware of this dynamic, and the more responsible ones address it by offering players the option to cancel a pending cheque withdrawal and redirect the funds back to their casino account or to a faster payment method. This option is not universal — some operators treat cheque withdrawals as irreversible once processing has begun — but where it exists, it gives the player a way out of the limbo state if they change their mind or if the wait becomes unbearable. Players who are prone to impulsive re-deposits should think carefully before initiating a cheque withdrawal, because the two-week wait is a test of discipline that many players fail.
The UKGC’s self-exclusion scheme, GamStop, applies to cheque withdrawals in the same way it applies to all other payment methods. A player who self-excludes through GamStop is blocked from accessing all UK-licensed gambling sites, and any pending cheque withdrawals at the time of self-exclusion are typically cancelled and returned to the player’s original payment method or held until the exclusion period ends. This is a sensible safeguard, but it creates a practical problem for players who initiated a cheque withdrawal before deciding to self-exclude: the cheque may be cancelled, and the funds may be locked in the casino account until the exclusion period expires. Players considering self-exclusion should cancel any pending cheque withdrawals first, to avoid this complication.
Reality checks — pop-up notifications that remind the player how long they have been gambling and how much they have spent — are required by the UKGC at regular intervals, and they appear regardless of the player’s preferred withdrawal method. For cheque-seeking players, the reality check serves a slightly different purpose: it reminds the player that the money they are gambling with is real money that will eventually arrive by cheque, slowly, and that every additional wager delays the moment when that cheque finally clears into their bank account.
A lost or undelivered casino cheque is an inconvenience, not a disaster, but the recovery process is slow and bureaucratic. The player contacts the casino’s customer support, reports the missing cheque, and the operator cancels the original instrument and issues a replacement. This process takes 5 to 10 working days from the point of cancellation, because the casino must verify that the original cheque was not deposited before authorising a new one. If the original cheque was stolen and deposited by a third party, the recovery process becomes significantly more complex, involving the casino’s bank, the player’s bank, and potentially law enforcement.
A casino cheque is a normal bank cheque drawn on the casino’s corporate account, and it can be deposited into any UK bank account and used like any other funds. Once the cheque clears — typically one working day under the Image Clearing System — the money is indistinguishable from salary, savings, or any other deposit. The cheque itself may carry the casino’s name on it, which means anyone who sees the physical instrument knows the source of the funds, but this is a cosmetic issue rather than a practical one.
Loyalty and VIP programmes at UK casinos typically award points based on wagering activity rather than withdrawal method, so choosing cheque over e-wallet does not affect the player’s loyalty status. However, some operators’ VIP tiers include perks like faster withdrawal processing or waived fees on certain payment methods, and these perks may not extend to cheque withdrawals. A VIP player at a UK casino might enjoy instant e-wallet withdrawals as a tier benefit while still waiting 10 working days for a cheque, because the cheque processing pipeline is separate from the VIP-accelerated digital pipeline.
No UK-licensed casino in 2026 offers cheque as the sole withdrawal method, because the UKGC expects operators to provide players with reasonable access to their funds, and a single slow payment method would not meet that standard. Every operator that supports cheque withdrawals also supports at least one faster alternative — usually debit card, PayPal, or bank transfer — and players are free to choose between methods on a per-withdrawal basis.
Gambling winnings are not subject to income tax in the UK for recreational players, regardless of the payment method used to receive them. A cheque withdrawal from a casino is treated the same as an e-wallet or bank transfer withdrawal for tax purposes: no tax is deducted at source, and the player has no obligation to report gambling winnings on a self-assessment return unless gambling is their primary source of income (in which case it is treated as trading income and taxed accordingly). The cheque itself does not create any additional tax reporting requirement, though it does create a physical document that a player could produce if HMRC ever questioned the source of a large deposit.
The cheque withdrawal space is surrounded by myths that persist because so few players use the method that corrections never circulate widely. The first myth is that cheque withdrawals are tax-free because they are “off the books” — this is nonsense, and it reflects a misunderstanding of both UK tax law and casino record-keeping. Every withdrawal, by every method, is recorded by the casino and reported to HMRC if the operator is required to do so under the Money Laundering Regulations. The cheque creates a paper trail, not an absence of one.
The second myth is that cheque withdrawals are safer than digital methods because they cannot be hacked. This conflates the security of the payment instrument with the security of the casino account. A casino account can be compromised regardless of the withdrawal method, and a hijacked account with cheque enabled means the attacker receives a physical cheque at the player’s address — which is arguably more dangerous than an instant e-wallet transfer, because the player may not notice the theft until the cheque arrives days later. Account security — strong passwords, two-factor authentication, avoiding public Wi-Fi for gambling — matters more than the withdrawal method.
The third myth is that casinos offer cheque withdrawals as a “courtesy” to players. Casinos are not charities, and nobody gives away free money — cheque withdrawals exist because a segment of the market demands them, and operators that serve that segment keep the option available to avoid losing those customers to competitors. The “courtesy” framing is marketing language that obscures the commercial reality: cheque support is a customer retention tool, not a gift.
The fourth myth is that cheque withdrawals are always free. As noted earlier, some operators charge fees of £5 to £25 per cheque, and even operators that advertise “free” cheque withdrawals may recover the cost through higher minimum withdrawal thresholds or longer processing times. The free cheque is like the free lollipop at the dentist — it exists to make the overall experience more palatable, not because anyone is being generous.
Cheque withdrawals make sense for a narrow set of UK players, and recognising whether you are in that set is more useful than reading another paragraph about clearing times. The player who benefits from cheque withdrawals is someone who values documentation over speed, who makes infrequent but large withdrawals, who has a land-based casino or bingo hall connection that makes cheque processing natural, and who has the patience to wait two weeks without re-depositing in the meantime.
The player who should avoid cheque withdrawals is anyone who gambles frequently, withdraws small amounts regularly, values instant access to winnings, or is prone to impulsive re-deposits during waiting periods. For this player, the cheque method is not just inconvenient — it is actively harmful, because the two-week wait creates a window of temptation that a faster payment method would eliminate.
For everyone else — and that is the vast majority of UK casino players in 2026 — the cheque route is a historical curiosity rather than a practical payment method. The UK casino market has moved decisively toward instant and near-instant withdrawals, and the operators that have invested in fast-payout technology (Sky Bet, BetMGM, bwin) are winning customers from slower competitors precisely because of that investment. The cheque survives at the margins, supported by land-based heritage and older demographics, but it is not where the market is heading.
The final word on cheque gambling belongs to the arithmetic. A player who makes four £500 withdrawals per year by cheque waits a combined 40 to 56 working days for their money, versus 40 to 56 hours for the same withdrawals by Skrill or PayPal. That is a difference of roughly 39 working days per year — nearly eight working weeks — spent waiting for money that is already theirs. Whether that wait is worth the documentation and physicality that a cheque provides is a question only the individual player can answer, but the cost of the wait is real, measurable, and entirely avoidable.

Share this post
Himalayan pink salt lamps have gained popularity as an interior design trend. Himalayan pink salt, which has a natural pink-red tint due to minerals, is
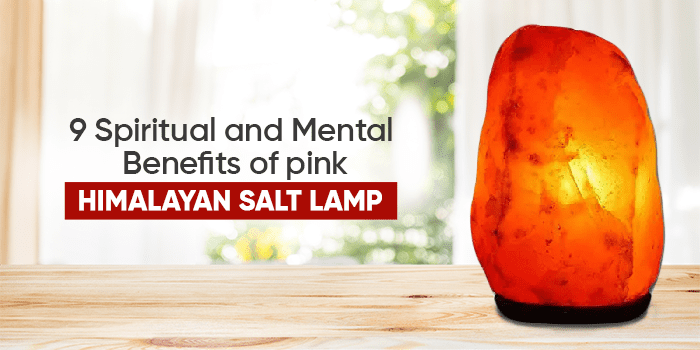

The Himalayan salt lamp is a salt rock crystal that comes from Himalayan Mountains in Asia. These lamps are made of chunks of pink Himalayan
The Christmas holiday season is about to end, no matter how freezing it is outdoors. The celebration of eating delicious foods and giving and receiving